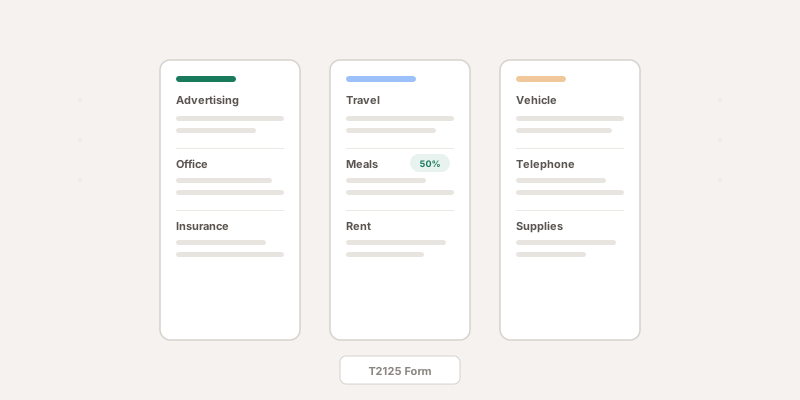
Form T2125, Statement of Business or Professional Activities, is the form self-employed Canadians attach to their T1 return to report business or professional income. The 2025 version has nine parts. Gross income ends up on line 8299. Part 4 has 21 expense lines, running from 8521 (Advertising) to 9270 (Other expenses). Business-use-of-home costs get their own line, 9945, in Part 5. Your final net income lands on line 9946, and that figure carries to line 13500, 13700 or 13900 of your return.
This guide follows the form from top to bottom. Every line number and label below was checked against the 2025 fillable T2125 and Guide T4002, Chapter 3 on October 29, 2026. Near the end there’s a filled-in example for a freelancer, so you can see how the numbers flow from one part to the next.
Whether you’re a real estate agent, an IT consultant or a rideshare driver, you use the same form. You fill in a separate T2125 for each business you run.
The form at a glance
| Part | What it does |
|---|---|
| Part 1 – Identification | Business name and number, fiscal period, industry code, cash or accrual method |
| Part 2 – Internet business activities | How many websites or platform pages earn you income, and what share of gross income they bring in |
| Part 3A / 3B | Business income (3A) or professional income (3B). Use one or the other, not both |
| Part 3C – Gross business or professional income | Lines 8000, 8290, 8230 and the total on 8299 |
| Part 3D – Cost of goods sold | Lines 8300–8519. Only for businesses that sell goods |
| Part 4 – Net income (loss) before adjustments | The 21 expense lines, ending at 9369 |
| Part 5 – Your net income (loss) | Partnership adjustments, 9945 business-use-of-home, net income on 9946 |
| Part 6 | Expenses partners paid themselves (feeds line 9943) |
| Part 7 – Calculating business-use-of-home expenses | Amounts 7A–7P |
| Parts 8–9 | Other partners and details of equity (9931–9933) |
| Areas A–G, Charts A–C | CCA schedule, asset additions and disposals, motor vehicle expenses, vehicle interest and lease limits |
Part 3: income lines
3A – Gross sales, commissions, or fees. Enter everything you billed, including the GST/HST you collected. A professional (an accountant or lawyer, say) uses 3H in Part 3B instead, which also includes work-in-progress.
3B – Deductions from 3A. Here you take out the GST/HST and PST that 3A contains, along with returns, allowances, discounts and GST/HST adjustments. The result is 3C.
3D–3F – Quick method only. If you use the quick method for GST/HST, the difference between the tax you collected and the tax you remitted counts as government assistance. You add it back as income here.
Line 8000 – Adjusted gross sales. This is 3C plus 3F (amount 3G), or 3N for professionals.
Line 8290 – Reserves deducted last year and line 8230 – Other income. Other income is where items like recaptured CCA go. The form’s own endnote sends recapture to line 8230.
Line 8299 – Gross business or professional income. This is 8000 plus 8290 and 8230. It goes on line 13499 (business), 13699 (professional) or 13899 (commission) of your return.
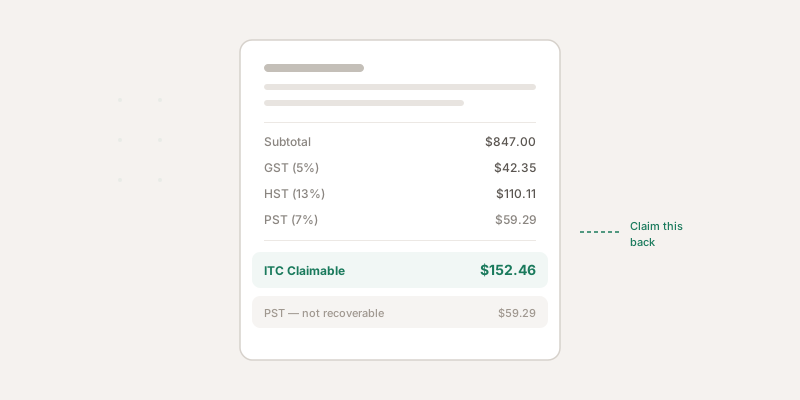
The form tells you how to treat sales tax in your expenses. If you claim input tax credits (ITCs), leave GST/HST out of your costs in Parts 3D, 4 and 5. If you use the quick method, leave it in. Get this wrong and you deduct the same tax twice: once as an expense and again as an ITC.
Part 3D: cost of goods sold (lines 8300–8519)
You only fill in Part 3D if you sell products. It starts with opening inventory (8300), then adds purchases (8320), direct wage costs (8340), subcontracts (8360) and other costs (8450). Closing inventory (8500) comes off the total. The result is cost of goods sold (8518) and gross profit (8519). Service businesses skip this part, and Part 4 then starts from line 8299 instead.
Part 4: the 21 expense lines
Enter only the business part of each expense. The form says so at the top of Part 4. The lines below appear in the order the form prints them. Each one links to our detailed page for that line.
8521 – Advertising
Ads, promotional material and website promotion. Canadian-content rules apply to print and broadcast media. Ads in Canadian periodicals are fully deductible only when at least 80% of the non-ad content is original editorial. Below that, half is deductible. Ads aimed mainly at Canadians but placed with a foreign broadcaster aren’t deductible at all.
8523 – Meals and entertainment
Generally capped at 50% of the lesser of what you spent and a reasonable amount. CRA lists a few exceptions. Long-haul truck drivers can deduct 80% of meals during an eligible travel period. You can host up to six office parties a year that are open to all staff at a location. Self-employed foot and bicycle couriers and rickshaw drivers can claim a flat $23 per day for meals (CRA, line 8523). Note who you ate with and why on every meal receipt.
8590 – Bad debts
Unpaid invoices you’ve decided in the year you’ll never collect. You can only deduct them if you already included that amount in income. If you use the cash method, you never reported the invoice, so there’s nothing to write off.
8690 – Insurance
Commercial premiums on business buildings, machinery and equipment, plus liability-type cover. Two common errors: vehicle insurance belongs on 9281 (Chart A), and home insurance belongs in Part 7 (9945). Most life insurance premiums aren’t deductible.
8710 – Interest and bank charges
Interest on money you borrowed for business purposes or to buy business property. What decides it is how you used the money, not the name on the loan. Interest on a loan for a passenger vehicle is limited (Chart B). For vehicles bought after 2023 the cap is $350 a month. Loan principal is never deductible. Some financing fees are spread over five years at 20% a year (CRA, line 8710).
8760 – Business taxes, licences, and memberships
Annual business licence fees, some business taxes (municipal business tax, for example), annual dues to trade or commercial associations, and subscriptions to publications. Dues for clubs whose main purpose is dining, recreation or sport aren’t deductible. The old version of this article sent licences and memberships to “Other expenses”. They have their own line, so put them here.
8810 – Office expenses
Small office consumables such as pens, paper clips, stationery and stamps. Desks, chairs, filing cabinets and calculators are capital property. Claim them through CCA on 9936. Furniture is normally Class 8 (20%).
8811 – Office stationery and supplies
Despite the label, CRA’s own guidance describes this line as things your business uses up to deliver its goods or services. Its examples are a veterinarian’s medicine, a plumber’s cleaning products, and the food and household supplies a daycare uses (CRA, line 8811).
8860 – Professional fees
Accounting, legal and other outside professional fees, including the cost of preparing your tax and GST/HST returns. Fees connected to buying capital property get added to that property’s cost instead.
8871 – Management and administration fees
Fees for running the business. CRA’s page for this line specifically names bank charges, including payment-processing charges (CRA, line 8871). Salaries, rent and property taxes are excluded because each has its own line.
The form label for 8710 also says “bank charges”, so CRA’s own documents point both ways for bank fees. Pick one line and use it every year.
8910 – Rent
Rent on business property: an office, a studio, a shop or land. Rent on your own home goes in Part 7, never here.
8960 – Repairs and maintenance
Labour and materials for minor repairs and upkeep of business property. You can’t deduct the value of your own labour. Repairs that improve an asset beyond its original condition are capital, so claim them through CCA. Vehicle repairs go on 9281.
9060 – Salaries, wages, and benefits
Gross pay for employees, plus your share as employer of CPP/QPP, EI and similar contributions. You can’t pay yourself a salary here. Drawings to yourself or your partners aren’t an expense. Wages paid to your spouse or child are deductible if the work was necessary, the pay was reasonable, and you actually paid it. You must issue T4 slips.
9180 – Property taxes
Property taxes on land and buildings your business uses. Property taxes on your home go in Part 7.
9200 – Travel expenses
Transportation, accommodation and meals while travelling to earn income. Meals on this line are still subject to the 50% limit. Your daily commute isn’t business travel.
9220 – Utilities
Telephone and utilities (gas, oil, electricity, water, cable) for business premises. The basic monthly rate for a home landline isn’t deductible, but business long-distance calls are. You can deduct the business share of cellphone airtime. Utilities for a home workspace go in Part 7, not here. (CRA’s web page for this line is still titled “Telephone and utilities”, but the 2025 form just says “Utilities”.)
9224 – Fuel costs (except for motor vehicles)
Fuel for business equipment, such as a generator, a compressor or a boat, plus motor oil and lubricants for that equipment. Fuel for your car or truck is not on this line. It goes in Chart A and ends up on 9281.
9275 – Delivery, freight, and express
Shipping, courier and freight costs you paid to get goods to customers or supplies to yourself.
9281 – Motor vehicle expenses (not including CCA)
This is the allowable total from Chart A. You add up fuel and oil, interest (limited by Chart B), insurance, licence and registration, maintenance and repairs, leasing costs (limited by Chart C) and electricity for zero-emission vehicles. You then multiply that total by business km ÷ total km. Business parking and supplementary business insurance are added on top at 100%.
There is no per-kilometre option on the T2125. The 73¢/km figure you may have seen is the 2026 limit for tax-free allowances an employer pays to employees (Finance Canada, Jan 2026). As a self-employed person you claim your actual costs and prorate them using a kilometre log. Our earlier version of this article got this wrong.
Per CRA, a log entry needs the date, destination, purpose and kilometres for each trip, plus odometer readings at the start and end of the year. Once you’ve kept a full 12-month base-year log, a 3-month sample log can support later years, as long as the business-use result stays within 10% of the base year.
9936 – Capital cost allowance (CCA)
Depreciation on capital property, taken from Area A. Enter it after removing any personal-use part and any CCA you’re claiming for your home (that goes in Part 7, amount 7K). Common classes: Class 8 (20%) for furniture and equipment, Class 50 (55%) for computers, Class 10/10.1 (30%) for vehicles, and Class 12 (100%) for small tools under $500 (CRA classes). The Class 10.1 cost ceiling is $38,000 for vehicles acquired in 2025 and $39,000 for vehicles acquired in 2026.
9270 – Other expenses
Legitimate business costs that don’t fit any line above. The form makes you specify each one. T4002 gives examples such as certain course costs, convention expenses, leasing of computers and other equipment, and a terminal loss on a CCA class. Use a specific line whenever one fits. A long, vague list here is harder to explain if CRA asks.
Line 9368 totals 4B to 4V, and line 9369 gives you net income (loss) before adjustments.
Part 5: from 9369 to your net income
- 5A: your share of line 9369. That’s 100% for a sole proprietor.
- 5B / 9974: journalism labour credit and the GST/HST rebate for partners. Most people leave these blank.
- 9943: other deductions from partnership income (Part 6). Partners only.
- 5D: net income after adjustments.
- 9945 – Business-use-of-home expenses: amount 7P from Part 7.
- 9946 – Your net income (loss): 5D minus 9945. This goes on line 13500, 13700 or 13900 of your return.
Part 7: business-use-of-home (7A–7P)
You add up heat (7A), electricity (7B), insurance (7C), maintenance (7D), mortgage interest (7E), property taxes (7F) and other costs such as rent or water (7G) to get 7H. Then you subtract the personal-use part (7I) and add any home CCA (7K) and last year’s carry-forward (7L). Your allowable claim (7P) is the lesser of that total and your net income after adjustments (7N). Anything left over carries forward (7O). That’s why a home office can reduce your business income to zero but can never create a loss. Who qualifies, how to work out the percentage, and how this differs from the employee T2200 claim are all covered in our business-use-of-home guide.
Worked example: a freelance designer’s 2025 T2125
Here’s an illustrative case with made-up but realistic numbers. Maya is a freelance graphic designer in Ontario, registered for GST/HST under the regular method. She has no inventory, no employees and no car, and she works from a rented apartment.
Income (Part 3A → 3C)
| Line | Amount |
|---|---|
| 3A Gross fees billed, including 13% HST | $67,800.00 |
| 3B HST included in 3A | −$7,800.00 |
| 3C / 3G / 8000 | $60,000.00 |
| 8299 Gross business income (→ line 13499) | $60,000.00 |
Expenses (Part 4, entered without HST because she claims ITCs)
| Line | What | Amount |
|---|---|---|
| 8521 | Portfolio-site ads, printed promo cards | $1,200.00 |
| 8523 | Client lunches: $800 spent × 50% | $400.00 |
| 8760 | Design-association dues, trade magazine subscription | $450.00 |
| 8810 | Paper, postage | $180.00 |
| 8811 | Proof printing and mounting boards used on client jobs | $620.00 |
| 8860 | Accountant (T1 business part + HST return) | $900.00 |
| 8871 | Bank account fees and card-processing fees | $540.00 |
| 9220 | Cellphone: $1,080 × 60% business use | $648.00 |
| 9270 | Design software subscriptions (specified) | $1,320.00 |
| 9368 | Total expenses | $6,258.00 |
| 9369 | Net income before adjustments | $53,742.00 |
Business-use-of-home (Part 7): Maya’s studio is a 120 sq ft room in a 1,000 sq ft apartment. It’s her principal place of business and she uses it only for work, so her business share is 12%.
| Amount | What | Value |
|---|---|---|
| 7B | Electricity | $720.00 |
| 7C | Tenant insurance | $300.00 |
| 7G | Rent (specified) | $24,000.00 |
| 7H | Subtotal | $25,020.00 |
| 7I | Personal-use part (88%) | −$22,017.60 |
| 7J / 7M | Business part (no CCA, no carry-forward) | $3,002.40 |
| 7N | Net income after adjustments (5D) | $53,742.00 |
| 7P → 9945 | Allowable claim (lesser of 7M and 7N) | $3,002.40 |
Line 9946: $53,742.00 − $3,002.40 = $50,739.60, which goes on line 13500 of her return.
Two things to notice. Her rent and electricity never touch lines 8910 or 9220, because Part 7 is their only home. And the 50% meal cut is applied before the amount goes on line 8523.
Where people most often misfile
- Car gas on 9224. Vehicle fuel goes through Chart A to 9281. Line 9224 is for fuel that doesn’t go into a vehicle.
- Home rent, utilities or insurance on 8910, 9220 or 8690. They all go in Part 7.
- Licences and association dues on 9270. Line 8760 exists for these.
- A desk or laptop on 8810. That’s capital property, so claim it through CCA on 9936.
- Your own “salary” on 9060. Drawings aren’t an expense.
- A per-km rate on 9281. Self-employed people claim actual costs × business-use %.
- GST/HST included in expenses while also claiming ITCs. Take it out, as the form instructs.
How ScanForTax maps receipts to these lines
ScanForTax has 21 expense categories, one for each Part 4 line from 8521 to 9270 (including 9936 CCA). When you scan a receipt, the AI suggests the line and pulls GST, HST and provincial tax (PST/QST) out as separate amounts. You can change the category during review or later. On a paid plan, the T2125 Worksheet export (CSV, Excel or PDF) totals your receipts by line number, applies the 50% cut to line 8523, and shows HST collected, ITCs and net HST for the year.
What it doesn’t do: it doesn’t keep a kilometre log, and it doesn’t fill in Chart A or Part 7 for you. Your receipts give you the totals. You apply your business-use percentages, from your log and your floor plan, before the amounts go on 9281 and 9945.
Try it with your own receipts. Your first 15 scans are free.
This article is for informational purposes only and is not legal, financial or tax advice. Line numbers and labels are from the 2025 Form T2125 and Guide T4002 as published on canada.ca. CRA can change both from year to year, so check the current versions at canada.ca and talk to a qualified tax professional about your own situation.